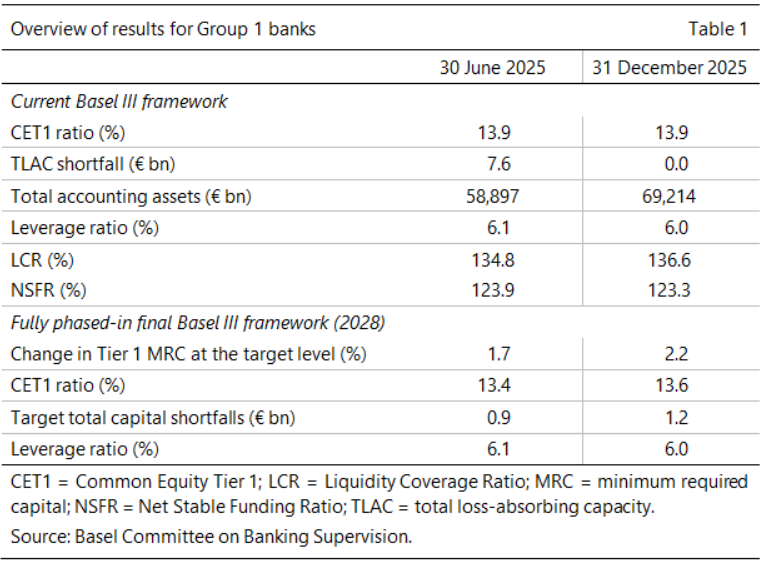
- As of the end of 2025, Basel III risk-based capital and leverage ratios remained stable for large internationally active banks compared with June 2025.
- The average Liquidity Coverage Ratio (LCR) of Group 1 banks improved slightly, while the Net Stable Funding Ratio (NSFR) decreased slightly.
- The average impact of the Basel III framework on Tier 1 minimum required capital (MRC) for Group 1 banks is +2.2%.
Basel III risk-based capital and leverage ratios remained stable, while Liquidity Coverage Ratios (LCRs) increased and Net Stable Funding Ratios (NSFRs) decreased slightly for large internationally active banks in the second half of 2025, according to the latest Basel III monitoring exercise, published today.
The report, based on data as of 31 December 2025, sets out trends in current bank capital and liquidity ratios and the impact of the fully phased-in Basel III framework, including the December 2017 finalisation of the Basel III reforms and the January 2019 finalisation of the market risk framework. It covers both large internationally active banks (Group 1) and other banks (Group 2). See note to editors for definitions.
The implementation of the final elements of the Basel III minimum requirements began on 1 January 2023.
At the end of December 2025, the average impact of the fully phased-in final Basel III framework on the Tier 1 minimum required capital (MRC) of Group 1 banks was +2.2%. This is slightly higher than the +1.7% impact recorded at the end of June 2025. This change, however, is driven by a bigger sample of banks in the latest Basel III monitoring exercise.
Group 1 banks report €1.2 billion of regulatory capital shortfall, compared with €0.9 billion at the end of June 2025.
The monitoring exercise also collected bank data on Basel III liquidity requirements. The weighted average LCR increased compared with the previous reporting period to 136.6% for Group 1 banks.
The weighted average NSFR decreased slightly to 123.3% for Group 1 banks. All banks in the sample reported an LCR and NSFR above the minimum requirement of 100%.
Note to editors
Through a rigorous reporting process, the Basel Committee regularly reviews the implications of the Basel III standards for banks and has been publishing the results of such exercises since 2012.
The results shown for “current Basel III framework” reflect the current jurisdictional standards that apply to the reporting banks as of 31 December 2025, which reflect different degrees of implementation of the Basel III reforms. The Basel III implementation dashboard provides an overview of Basel III implementation status across jurisdictions. The results shown for “fully phased-in final Basel III framework (2028)” assume that the positions as of 31 December 2025 were subject to the full application of the Basel III standards. That is, they do not account for transitional arrangements set out in the Basel III framework, which expire on 1 January 2028. No assumptions were made about bank profitability or behavioural responses, such as changes in bank capital or balance sheet composition. For that reason, the results of the study may not be comparable with industry estimates.
Data are provided for 149 banks, including 106 large internationally active banks. These “Group 1” banks are defined as internationally active banks that have Tier 1 capital of more than €3 billion and include 29 institutions that have been designated as global systemically important banks (G‑SIBs). The Basel Committee’s sample also includes 43 “Group 2” banks (ie banks that have Tier 1 capital of less than €3 billion or are not internationally active).
The values for the previous period may differ slightly from those published in the previous report. This is because, first, some banks have updated their earlier data to improve accuracy and expand the dataset over time. Second, additional national Pillar 1 requirements have been included to give a clearer picture of how Basel III affects banks' target capital requirements. For more information, you can refer to the Basel III monitoring methodology note.